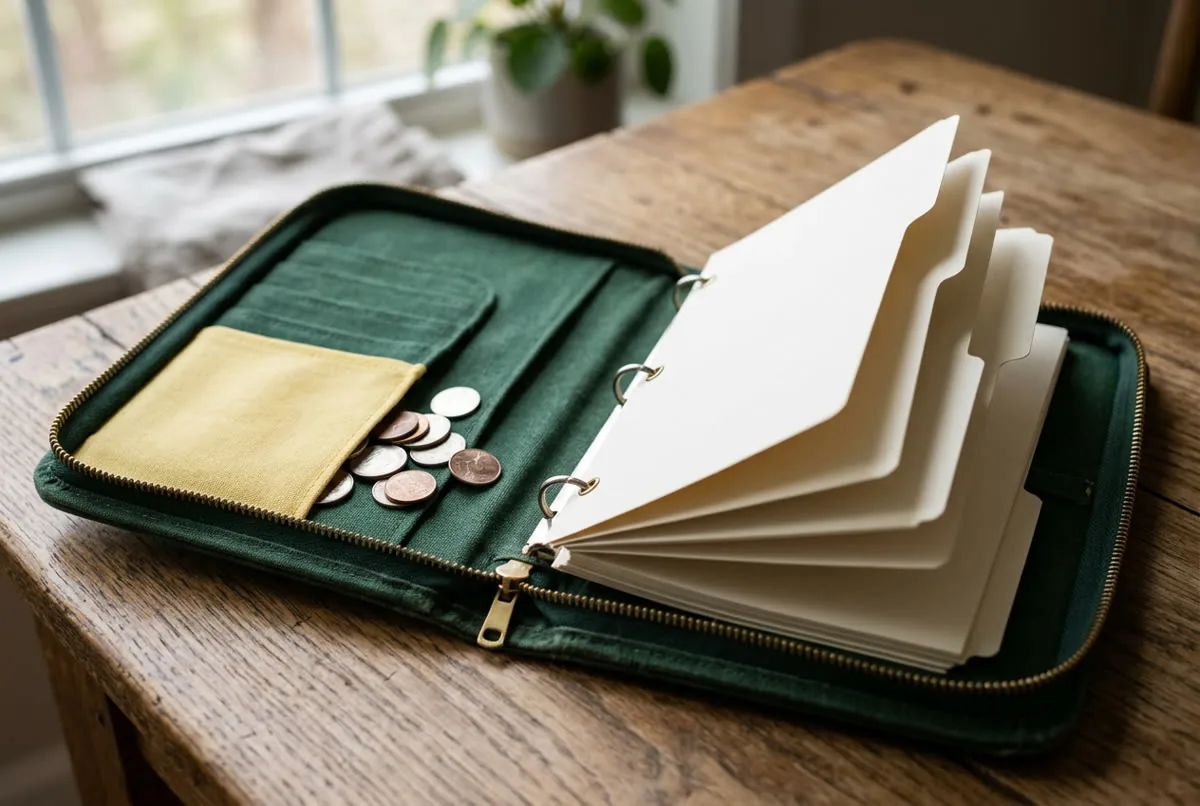
Every sinking fund list looks the same: a long, satisfying scroll of categories that all feel equally urgent. That’s the problem. Fifty categories with the same visual weight tells you nothing about which one to fund first, or how many will actually fit in the binder you’re about to buy. This list sorts the same kind of categories into three priority tiers, so you can build a real system instead of a wish list.
How we sorted it: each category earned its tier by asking one question: how often does it land, and how much damage does it do when it catches you off guard? Frequent, expensive, and easy to forget lands in Tier 1. Predictable but smaller or more seasonal lands in Tier 2. Optional and lifestyle-driven lands in Tier 3. If you’re new to the mechanics of sizing a fund, how to set up sinking funds covers the five-step method this list assumes.
Tier 1: Fund these first
These are the categories that do the most damage when they hit and you weren’t ready. If you only run three sinking funds this year, pull them from here.
| Category | What triggers it | How to size it |
|---|---|---|
| Car maintenance & repairs | Ongoing, no fixed date | Estimate last year’s total, divide by 12 |
| Auto insurance | Every 6 or 12 months, in one lump | Premium ÷ months until the next bill |
| Vehicle registration & inspection | On your state’s renewal cycle | Cost ÷ months until renewal |
| Home or renters insurance | Annually | Premium ÷ 12 |
| Property taxes | Once or twice a year, if not escrowed into your mortgage (CFPB) | Bill ÷ months between bills |
| Home & appliance repairs | Irregular, but guaranteed eventually | Rough annual estimate ÷ 12 |
| HOA or association dues | Quarterly or annually | Total ÷ months between bills |
| Quarterly estimated taxes | Four payment periods a year, if self-employed (IRS) | Each payment ÷ months until it’s due |
Notice these are the boring ones. Boring and predictable is exactly what makes them perfect sinking-fund material: there’s no guesswork about whether the expense is coming, only about when.
Tier 2: Family, seasonal, and health
These land less often than Tier 1, but they cluster around specific times of year and specific stages of raising a family, which is exactly what makes them easy to forget between occurrences.
| Category | What triggers it | How to size it |
|---|---|---|
| Holiday gifts & hosting | December, mostly | Last year’s total ÷ 12 |
| Back-to-school supplies & fees | Once a year, usually August | Estimated cost ÷ months you have |
| Kids’ activities & sports | Per season or per registration | Season fee ÷ months between seasons |
| Birthday parties (hosting + gifts) | Multiple times a year | Rough yearly total ÷ 12 |
| Medical & dental copays | As needed, but predictable in volume | Typical annual spend ÷ 12 |
| Vision care | Annually or every other year | Exam + glasses cost ÷ 12 or 24 |
| Prescriptions filled in bulk | Quarterly | Refill cost ÷ 3 |
| Braces or orthodontics | Monthly payment plan or lump sum | Total ÷ payment months |
| Annual physicals & wellness visits | Once a year | Expected out-of-pocket ÷ 12 |
| Childcare gaps (breaks, snow days) | A handful of times a year | Rough total ÷ 12 |
| Clothing as kids grow | Seasonally | Seasonal estimate ÷ 3 |
| Family vacation | Once or twice a year | Target total ÷ months of saving |
This is the natural halfway point to actually write your funds down instead of just reading about them. Our free budget guide can help, so every category you pick from this list gets a real line instead of floating in your head. Grab the free budget guide and start filling in your Tier 1 and Tier 2 picks.
Tier 3: Lifestyle, pets, and the fun stuff
Sinking funds aren’t only for dread. This tier is optional, and that’s the point: fund it once your first two tiers are running, not before.
| Category | What triggers it | How to size it |
|---|---|---|
| Pet food bought in bulk | Monthly or quarterly | Bulk cost ÷ months it lasts |
| Vet visits & vaccinations | Annually, plus occasional surprises | Typical annual spend ÷ 12 |
| Annual subscriptions (streaming, software, memberships) | Once a year, in one charge | Total ÷ 12 |
| A big planned purchase (phone, laptop, furniture) | Whenever you decide | Target price ÷ months until you want it |
| Hobbies & classes | Per session or per season | Cost ÷ months between sessions |
| Weddings you’re invited to | A handful of times a year | Gift + outfit + travel ÷ 12 |
| Concerts & events | A few times a year | Rough total ÷ 12 |
| Charitable giving | Ongoing or seasonal | Target amount ÷ 12 |
| Warehouse club or association memberships | Annually | Fee ÷ 12 |
| A just-for-fun fund | Whenever | Whatever amount feels good, guilt-free |
How many categories fit in one binder
Here’s the part most category lists skip: the categories are only useful once they have a physical or digital home, and that home has a capacity limit.
A cash envelope binder built for named categories, like the Sooez Cash Envelope Kit, ships with a set of labeled pockets. That’s enough for a beginner’s first handful of categories, but it’s not enough to run all three tiers of a full list at once, and it isn’t meant to be. The offer button below has the details if that’s the format you want. A general zipper binder, like the Antner A6, runs a similar handful of zipper pockets and is built more for everyday cash stuffing than for pure sinking funds, but it flexes into this job fine too.
The practical rule: count your active categories, the ones you’re actually funding this year, not the full menu above. If that number is 6 to 12, a labeled binder handles the whole system in one place, and each pocket becomes one line on your budget. If you’re past 12 active categories, keep the smaller, frequent ones (holidays, kids’ activities, the fun fund) in the binder where you can see them fill up, and move the larger, slower-growing ones (car repairs, home repairs, property taxes) into named sub-accounts inside a high-yield savings account instead. You don’t need a bigger binder. You need a second home for the categories that have outgrown one.
Mistakes that quietly sink the system
Naming a category too broadly. “Miscellaneous” isn’t a sinking fund, it’s a place money disappears. Name each pocket for one specific thing so you know instantly whether it’s overfunded or empty.
Opening every category on day one. Twenty new funds by Sunday night is a system nobody keeps up. Start with Tier 1, prove you can maintain three or four, then add a tier.
Letting categories share a pocket “just this once.” The moment two categories mix, whichever one you spend on first quietly eats the other. Keep them visually separate, whether that’s binder pockets or named sub-accounts.
Sizing by guess instead of last year’s real number. A hopeful $300 Christmas fund that was actually $600 last year runs dry in November, every time. Use your real number, not the one you wish were true.
Start with three categories this week
You don’t need all three tiers running by Friday. Pick two from Tier 1 and one from Tier 2, the ones that made you wince reading this list, estimate each one’s yearly total, and divide by the months you have. That’s your starting system.
Put the numbers on paper before you buy anything: grab our free budget guide, write your first three categories on the budget template, and decide from there whether a labeled binder or a savings sub-account is the right home for each one. For the full method behind the math, see how to set up sinking funds, and for a month-by-month view of when your funds are due, our sinking fund calendar maps the whole year at once. More systems like this live in our budgeting basics library.
Frequently Asked Questions
- What's the difference between this list and a regular sinking fund category list?
- Most lists, including our own roundup of 50 sinking fund categories you're forgetting, are menus you scan for ideas you forgot. This one sorts every category into three priority tiers, so instead of 50 equal-weight bullet points you get a clear order to fund them in, plus guidance on how many will actually fit in a binder or a set of savings sub-accounts. Use the 50-category list to brainstorm, then use this one to decide what to build first.
- How many sinking fund categories should I actually track?
- Enough to cover your real budget-wreckers, not enough to need a spreadsheet to remember them. A manageable range is usually five to twelve active funds: two or three from Tier 1, a handful from Tier 2, and one or two Tier 3 categories for the fun stuff. Start with Tier 1 only if you're brand new, and add a tier at a time as the habit sticks.
- Should sinking fund categories live in a binder or a savings account?
- Either works, and plenty of people use both. A labeled binder or envelope kit is great for categories you want to see and touch, usually the ones under a few hundred dollars where physical limits help you stop overspending. A high-yield savings account with named sub-accounts is better for categories that grow large before they're due, like a car repair fund, since it isn't cash sitting in a drawer. Pick based on the category, not a single system for all of them.
- How many binder pockets do I need for a full sinking fund system?
- Count your active categories, not the full menu of possible ones. A binder of labeled pockets, like the Sooez Cash Envelope Kit, works well for a beginner's first handful of categories. Once you're running more than 10 to 12 named categories, it's usually easier to keep the smaller ones in the binder and move the larger, slower-growing ones into savings sub-accounts instead of buying a second binder.
Sources & references
Before you go
The Already-Done Budget: Pre-Filled Starting Numbers for a Real Household Budget
A budget that starts filled in: 13 categories with realistic starting percentages from the 50/30/20 rule, pre-computed dollar amounts by income, and a worksheet to swap in your real numbers.
Free guide
The Already-Done Budget: Pre-Filled Starting Numbers for a Real Household Budget
A budget that starts filled in: 13 categories with realistic starting percentages from the 50/30/20 rule, pre-computed dollar amounts by income, and a worksheet to swap in your real numbers.